Blog / Taxes
How much should a roofing company set aside for taxes?
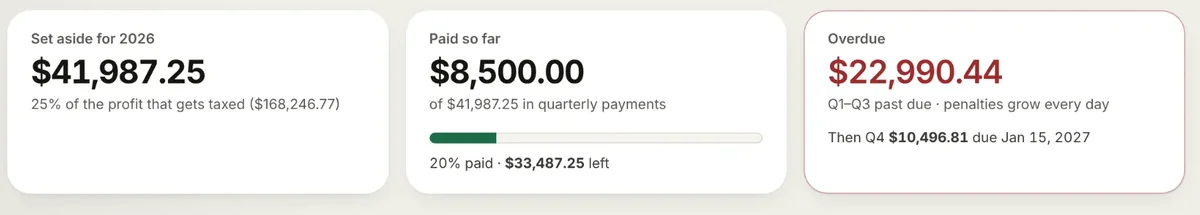
Most roofing owners find out their tax number in March, when the CPA finishes the return. By then the money is spent and nothing about last year can change.
You can avoid that surprise. You need three things: the right number to set aside from, a rough percentage, and a few dates on the calendar.
Set aside from profit, not revenue
Income tax and self-employment tax are charged on what the business kept, not on what it billed. A $1.2M year can mean $300K of profit or $40K, and the tax bill is very different.
So the first number you need is profit: what customers paid, minus job costs (materials, crews, subs, dumpsters, permits) and overhead (office, trucks, insurance, marketing).
| Example year | Amount |
|---|---|
| Revenue collected | $1,200,000 |
| Job costs: materials, crews, subs | −$840,000 |
| Overhead: office, trucks, insurance | −$190,000 |
| Profit | $170,000 |
| Set aside at 25–30% of profit | $42,500–$51,000 |
Example data for a fictional company.
A rough starting point: 25 to 30 percent of profit
Many owners of single-owner companies use 25 to 30 percent of profit as a first set-aside. It is a cushion, not a calculation. Your real number depends on:
- How the company is set up. A sole proprietor or single-member LLC usually pays self-employment tax (15.3 percent on most of the profit, up to an annual cap) plus income tax. An S-Corp owner pays through payroll on their salary, and the rest is taxed differently.
- Your state. Some states have no income tax, others add several percent.
- Other income and deductions in your household.
Use the percentage to stop guessing today. Ask your CPA to turn it into a real number once a quarter.
Why the April bill can be bigger than you think
If you don't send quarterly estimated payments, the full year lands at once, often with an underpayment penalty on top. The IRS generally does not charge that penalty if your estimates for the year cover at least one of these:
- 90 percent of this year's tax, or
- 100 percent of last year's total tax (110 percent if last year's adjusted gross income was over $150,000).
Your CPA can tell you which one is easier for you to hit.
Winter dates for roofing owners
| Date | What happens |
|---|---|
| Before December 31, 2026 | Last chance to review 2026 with your CPA while you can still make decisions that count for this year. |
| January 15, 2027 | Fourth-quarter estimated tax payment for 2026 is due. |
| February 1, 2027 | Forms 1099-NEC for subcontractors are due to them and to the IRS (January 31 falls on a Sunday this time). |
New for 2026: the reporting threshold for Form 1099-NEC went up from $600 to $2,000 for payments made in 2026. Ask your CPA which of your subs need one, and collect a W-9 from every sub now, not in late January.
How to actually keep the money
- Open a separate savings account just for taxes. Money you can't see in the operating account is money you won't spend.
- Move a fixed share every time a job pays. For example, 10 percent of every customer payment. On a job with a 30 percent margin, that is roughly a third of the job's profit.
- Check the estimate monthly, not once a year. A good summer can push the number up fast.
- Send your CPA clean numbers every quarter, so the estimate is based on real profit, not a guess.
The short version
Know your profit, set aside 25 to 30 percent of it until your CPA gives you a real number, keep it in a separate account, and put January 15 and February 1 on the calendar today.
Trinity keeps a running tax estimate from your real books, updated every week, so the number is never a surprise. Your CPA still files. We get the numbers ready.
This article is general information, not tax, legal or accounting advice. Trinity CEO is not a CPA firm. Talk to your CPA about your situation.